Archive

September 2026

Browsing

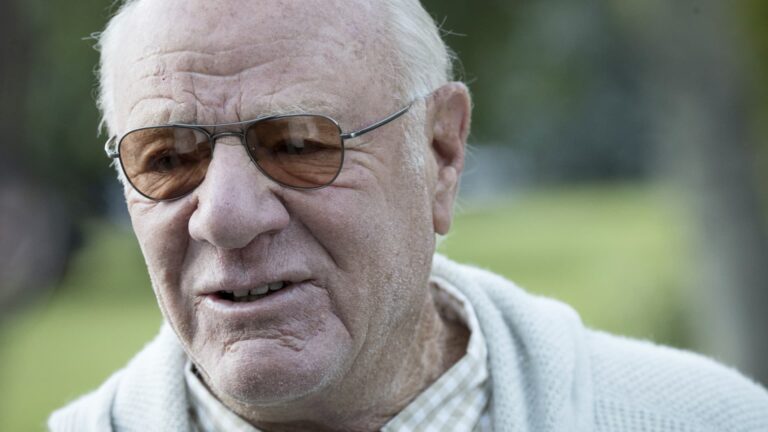
Shares of MGM Resorts International took a sharp dive on Thursday, tumbling roughly 11 percent after Barry Diller’s People Inc. officially withdrew its proposal to acquire the gaming giant. The sudden reversal comes nearly four months after Diller first offered to take the company private at a price of 48.30 dollars per share. While People Inc., formerly known as IAC, already holds a substantial 26.1 percent stake in MGM, the bid for full ownership has fallen through.

In a press release accompanying the announcement, Diller described the decision as a result of the complex variables involved in such a massive transaction. He noted that there are many ingredients required to bring a proposal like this to completion and admitted that the specific mix simply wasn’t coming together as his team had envisioned. Industry analysts suggest that the financial burden played a major role, with reports indicating that Diller grew concerned over the significant amount of debt the acquisition would have saddled upon the company.

Despite pulling back from the current offer, Diller left the door open for potential future collaborations. He stated that People Inc. remains interested in exploring various strategic transactions with MGM Resorts and looks forward to evaluating other alternatives moving forward. This suggests that while a total buyout is off the table for now, the relationship between the two entities remains cordial and strategically aligned.

The volatility comes during a period of high activity within the gambling industry. Just earlier this week, shareholders of Caesars Entertainment gave their approval for billionaire Tilman Fertitta to acquire that company in a deal valued at 17.6 billion dollars, which will see Caesars shareholders receive 31 dollars per share in cash. As competitors consolidate, investors are keeping a close eye on whether MGM will seek another suitor or pivot its strategy following this setback.
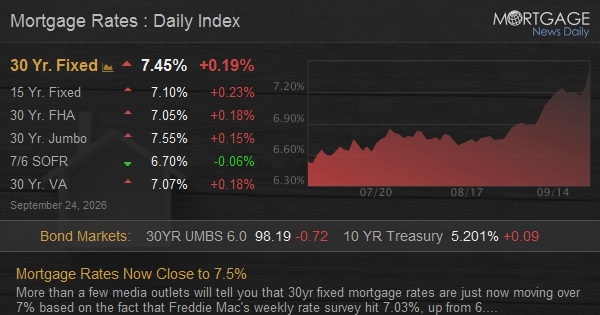
Homebuyers looking at current listings may find themselves facing a harsher reality than some headlines suggest. While several media outlets are reporting that 30 year fixed mortgage rates have only recently crossed the 7 percent threshold, those numbers often rely on delayed surveys that don’t reflect the immediate market. For instance, recent figures from Freddie Mac show a slight uptick to about 7.03 percent, but because that data is an average taken over a five day period, it fails to capture the rapid climb happening in real time.

The truth is that the 7 percent mark was actually breached weeks ago, and since then, rates have continued to surge. Daily tracking indices now place the actual cost of borrowing closer to 7.45 percent. While some lenders might still quote rates in the high six percent range to attract customers, these offers typically require significant upfront costs or points to buy down the rate. When comparing these quotes on an apples to apples basis without those hidden fees, the trend line is clearly pointing upward toward 7.5 percent.

This sudden spike is being driven by a perfect storm of economic pressures including rising oil prices and unexpectedly strong economic data. These factors have fueled fears that the Federal Reserve will need to accelerate its path of interest rate hikes to combat inflation. With more economic reports due next week, borrowers remain anxious that further volatility could push monthly payments even higher, making an already tight housing market feel increasingly out of reach for many families.

Wall Street entered Wednesday on a cautious note as stock futures trended slightly lower, erasing some of the optimism following a historic run for the tech sector. While the Nasdaq Composite recently soared to a new all-time intraday high and closed at a record level on Tuesday, investors are now grappling with renewed volatility. Early indicators show modest dips across the board, with S&P 500 and Nasdaq-100 futures sliding alongside a drop in Dow Jones futures.

Much of this hesitation stems from fluctuating energy markets and geopolitical tension between the United States and Iran. Oil prices have shifted unpredictably after President Donald Trump described a recent three hour meeting with Iranian officials as very good, though he simultaneously noted he faces a big decision regarding whether to pursue a diplomatic deal or take more drastic measures against Tehran. These tensions pushed Brent crude oil toward 100 dollars a barrel, adding pressure to global equities and dragging down European shares throughout Wednesday morning.

Domestic economic concerns are further complicating the landscape. Treasury Secretary Scott Bessent indicated that the government is considering a potential ban on diesel exports to combat rising fuel costs, while mortgage rates have surged to levels not seen since 2024. Additionally, warnings from Boston Fed President Susan Collins suggest that inflation may remain notably higher than the central bank’s two percent target, signaling that borrowing costs could stay elevated for longer than some hopeful traders anticipated.

Despite these headwinds, certain sectors continue to find momentum. Quantum computing firm IonQ saw its shares jump over thirteen percent following a technical breakthrough in error decoding, and AI drone maker Tekever reached a massive six point four billion dollar valuation driven by demand for defense technology in Ukraine. As analysts like Brett Ewing maintain bullish long term targets for the S&P 500 reaching as high as 8,200 by year end, today’s mixed performance suggests a tug of war between technological innovation and macroeconomic instability.

Investors are bracing for a volatile session this Wednesday as a flurry of economic data and corporate earnings reports threaten to shake up the current market trajectory. Analysts are keeping a close eye on several key catalysts that could dictate whether indices climb higher or retreat into a defensive crouch. From shifts in Federal Reserve sentiment to unexpected movements in treasury yields, the day promises plenty of action for both institutional traders and retail investors.

The primary focus remains centered on high growth tech stocks and their sensitivity to incoming inflation markers. As companies prepare to unveil their quarterly results, the street is looking for signs that artificial intelligence investments are finally translating into tangible revenue streams rather than just speculative hype. Any guidance suggesting a slowdown in spending could trigger a broader sell off across the Nasdaq, while positive surprises might fuel another leg of the rally.

Beyond the tech sector, commodity price swings and geopolitical tensions continue to add layers of uncertainty to the trading floor. Energy stocks are expected to react sharply to updated inventory levels, while global trade signals may impact multinational corporations with heavy overseas exposure. Traders will be scanning these indicators closely throughout the afternoon to determine where the safest harbors lie amid an increasingly unpredictable financial landscape.

The release of Meta’s new consumer AI product, Muse, has sent fresh shockwaves through the financial sector, reigniting deep seated fears that artificial intelligence will dismantle the traditional brokerage model. While Meta insists that Muse will not execute trades or provide direct financial advice, the tool’s ability to analyze portfolios and track investment goals suggests a future where expensive middlemen are no longer necessary. This shift is creating a stark divide in the market, pitting established giants against agile, tech forward challengers.

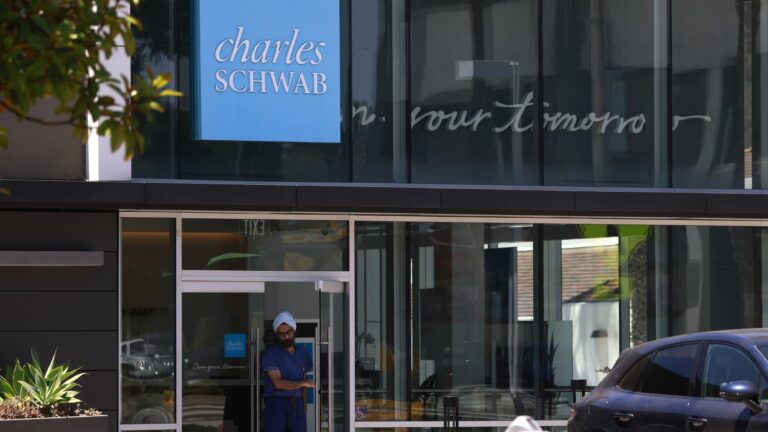
Charles Schwab has emerged as a primary target for investor anxiety, with shares sliding six percent Tuesday to hit their lowest level since early July. The broader industry felt the pinch as well, with LPL Financial Holdings and Raymond James Financial both seeing significant dips. Analysts suggest that legacy firms relying on fee structures for reporting and trading are particularly vulnerable to disruption. Some experts argue that while Meta might not replace custodians entirely, it could strip away the value proposition of advisors who charge premiums for tasks that an AI agent can now handle in seconds.

In contrast, Robinhood appears to be riding the wave of disruption rather than being drowned by it. The retail focused brokerage saw its stock climb toward another year to date high, bolstered by its own aggressive rollout of AI agents capable of managing portfolios on behalf of users. Younger investors from Gen Z and the millennial cohort continue to gravitate toward these streamlined platforms, viewing them as more trustworthy and innovative than their older counterparts.

The volatility is reflected clearly in the options market, where traders are placing heavy bets against Schwab while doubling down on Robinhood. A surge in put options indicates a growing belief that Schwab’s stock could drop further over the coming months. As AI continues to remove the friction from investing, the battle lines are drawn between those trying to protect historical market shares and those building a decentralized, automated future for finance.

The stock market faced a challenging session on Wednesday as major indexes struggled to maintain momentum following a recent record high for the Nasdaq. Investors reacted cautiously to new economic data that came in hotter than expected, sparking fears that persistent inflation could complicate the broader financial outlook. While some sectors attempted to hold their ground, the overall mood turned bearish as traders weighed the implications of a resilient economy against potential interest rate pressures.

Small cap stocks bore the brunt of the downturn, leading the slide across various exchanges. This volatility was particularly evident in the technology sector, where several heavy hitters saw significant losses during midday trading. Alphabet emerged as one of the most notable decliners among big tech companies, signaling a shift in sentiment away from growth-oriented assets as investors shifted toward more defensive positions.

The semiconductor industry took an especially hard hit throughout the day. Chipmakers such as Micron Technology and Sandisk tumbled alongside Monolithic Power, dragging down expectations for a continued rally in hardware and AI infrastructure. This synchronized drop suggests that analysts may be recalibrating valuations for chip firms after an aggressive run upward, leaving many portfolios in the red as the live coverage continues into the afternoon.

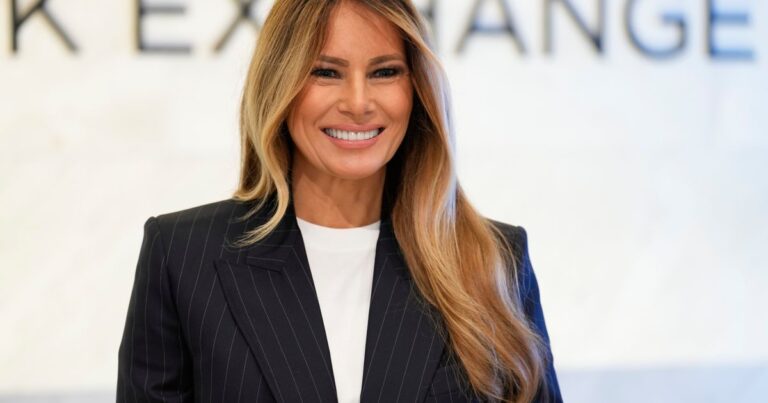
Melania Trump took center stage at the New York Stock Exchange on Wednesday morning, ringing the opening bell to mark the official launch of Imperia. The new initiative aims to empower women to secure greater economic influence and ascend into leadership roles across various industries. Comprised of a network of CEOs, founders, and entrepreneurs, Imperia represents a strategic shift for the first lady, moving beyond her previous focus on children to leverage her own business acumen in support of female financial independence.

Speaking to members of the group, Mrs. Trump emphasized that while previous generations fought simply for a seat at the table, the current mission is about ownership and creating opportunities for those who follow. She argued that true power comes from controlling equity, real estate, capital, and intellectual property. According to the first lady, many people still underestimate the scale of women’s impact on the global economy, asserting that women are not merely participants in the marketplace but serve as its very foundation and infrastructure.

The appearance coincided with a wider media push, including a rare interview on Fox & Friends where she addressed her evolving role in the public eye. Responding to suggestions that she has appeared less frequently than during her husband’s first term, she explained that her reduced visibility is a result of focusing more intensely on tangible outcomes behind the scenes. She pointed toward her involvement in preparing for Chinese President Xi Jinping’s state visit and her diplomatic efforts to reunite families separated by the conflict between Russia and Ukraine as evidence of her active workload.

Beyond her economic initiatives and humanitarian work, Mrs. Trump also teased upcoming creative projects. Following a previous documentary about her life around the time of Donald Trump’s second inauguration, she announced a new two-part docuseries arriving this fall. Describing it as a more intimate experience involving one-on-one conversations, she suggested that viewers can expect answers to private questions that have never been shared publicly before.

The meteoric rise of ChatGPT has done more than just change how people write emails or brainstorm ideas; it has ignited a massive gold rush in the financial markets. By bringing generative AI into the mainstream, OpenAI sparked a wave of investor enthusiasm that propelled both the S&P 500 and the Nasdaq Composite to record heights. While retail investors cannot buy shares of OpenAI directly, they have pivoted toward the tech titans providing the backbone for this revolution. With the global generative AI market projected to skyrocket from roughly 161 billion dollars in 2026 to over 1.2 trillion dollars by 2034, the stakes for these companies have never been higher.

Among the heavy hitters leading the charge is Alphabet, whose Gemini model is now deeply woven into everything from Google Search to Pixel smartphones. The company isn’t just focusing on software, however, as it develops its own custom AI accelerator chips and leverages its DeepMind division for groundbreaking scientific research. Meanwhile, Microsoft has solidified its position as a primary gateway to AI through its multi-billion dollar partnership with OpenAI. By integrating Copilot across its ecosystem and scaling its proprietary MAI reasoning models, Microsoft has already seen tens of millions of paid users adopt its AI productivity tools.

Other industry leaders are carving out their own niches to ensure they aren’t left behind. Amazon has transformed its AWS cloud platform into a comprehensive hub for AI infrastructure and launched Alexa Plus to turn its home assistant into a truly conversational agent. Simultaneously, Meta Platforms is taking a different path by championing an open source philosophy. Through its Muse Spark model line, Meta is embedding advanced AI assistants across Facebook and Instagram, betting that widespread accessibility will drive long term dominance in the social media landscape. Together, these firms represent a diverse bet on a future where generative AI manages everything from corporate logistics to creative expression.

The precious metals market has entered a period of extraordinary volatility and growth, with gold, silver, and copper all hitting record highs throughout 2026. A cocktail of geopolitical instability, disrupted supply chains, and staggering government debt has driven investors toward hard assets for safety. Gold peaked at over 5,500 dollars per ounce in January, while silver soared past the 100 dollar mark. Even with the Federal Reserve raising interest rates to combat inflation—a move that typically hurts gold—the market has remained resilient thanks to aggressive purchasing from central banks, particularly in China.

Speaking at the Metals Investor Forum in Vancouver, Robert Sinn of Goldfinger Capital suggested that while these price surges are impressive, the real opportunity is just beginning to shift. According to Sinn, commodity cycles generally move through five distinct stages: starting with the raw metals themselves, then moving to major producers, then to developers, followed by exploration juniors, and finally ending in a state of speculative mania. While the giants like Newmont and Barrick have already filled their coffers with cash during the producer phase, Sinn believes we are now entering the fourth stage where capital begins to trickle down to smaller discovery plays.

This transition is becoming evident as major mining firms and institutional investors begin writing significant checks to junior miners with high quality assets. Recent examples include substantial financing rounds for companies like Snowline Gold and strategic investments from JPMorgan into Perpetua Resources. Furthermore, unlike previous cycles, current trends are being bolstered by unprecedented direct involvement from governments in the US, Canada, and Europe seeking to secure critical mineral supplies for national security reasons.

Crucially, Sinn argues that despite the record breaking prices, the market is far from a bubble. He noted that we have not yet seen the reckless behavior or fraudulent schemes that characterized historical crashes like those following Bre X or the Hunt brothers’ attempt to corner the silver market. Because the current rally is grounded in fundamental demand and corporate liquidity rather than blind speculation, Sinn believes there is still considerable upside ahead for investors targeting advanced junior explorers who possess assets that majors are eager to acquire.

The scale of current investments in artificial intelligence has reached a fever pitch, with hyperscalers ramping up capital expenditures to historic levels. Recent data from Goldman Sachs highlights the intensity of this boom, noting that AI related issuers now make up a quarter of all new US investment grade corporate debt. For many of the world’s most creditworthy companies, spending has surged by at least thirty five percent annually for ten consecutive quarters. However, beneath these staggering numbers lies a growing tension between genuine structural demand and speculative fervor.

Lu Zhang, the founder and managing partner of Fusion Fund, suggests that the signal to noise ratio in the current market is dangerously low. While she acknowledges that big tech firms are determined to secure their computing power to avoid being left behind by competitors, she warns that much of the apparent demand may be illusory. Financial red flags have already begun to emerge, with giants like Microsoft, Alphabet, Amazon and Meta seeing capital spending grow significantly faster than their revenues. In some cases, free cash flow has plummeted or turned negative, leading critics to wonder if some of this growth is merely circular vendor financing rather than organic market expansion.

To cut through the hype, Zhang employs a rigorous three part test when evaluating AI ventures. Rather than focusing on model quality or massive spend totals, she looks for companies that possess curated industry specific data, optimized architectures that lower operational costs beyond mere training, and established partnerships with key industry players who control essential workflows. Without these pillars, Zhang argues that any perceived competitive advantage is likely temporary. She believes true durability is found not in headline revenue figures—which can be inflated in a seller’s market—but in actual budget allocations from non tech sectors like healthcare and insurance.

Beyond the balance sheets, Zhang identifies governance failures as one of the primary risks that could derail the AI thesis entirely. High profile security breaches and pauses in model development due to safety concerns illustrate how quickly regulatory or ethical lapses can freeze progress. As global powers discuss international safety standards and emergency hotlines to manage AI incidents, the industry faces a reckoning where technical capability must finally align with responsible oversight to ensure long term stability.