Author

admin

Browsing

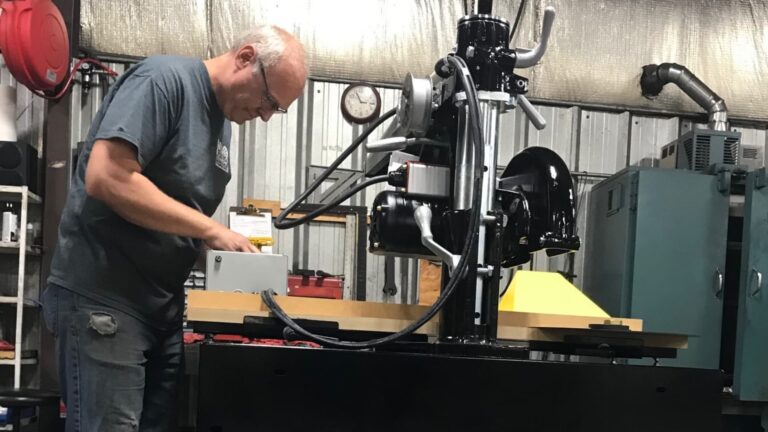
For Allen Eden, the owner of Original Saw Co. in Britt, Iowa, the current economic climate feels less like a dip and more like a vice. His business produces industrial power saws, but lately, he has spent more time worrying about the skyrocketing cost of basic components than the machines themselves. One small motor bracket that once cost forty two dollars recently jumped to eighty seven dollars. To protect himself from future spikes and unpredictable shortages, Eden has begun hoarding inventory, a risky move when financing that stock is becoming increasingly expensive. It is an awful situation, he says, reflecting a sentiment shared by thousands of mid sized manufacturers across the country.

American companies are currently trapped in a punishing three way squeeze. Trade tariffs have driven up the price of raw materials like steel and aluminum, while geopolitical instability has sent fuel costs soaring, making it more expensive to manufacture and ship goods. Now, the Federal Reserve’s decision to raise interest rates to combat inflation has added a third layer of pressure. For smaller businesses that rely on short term loans rather than deep cash reserves, these rate hikes translate immediately into higher operating costs, leaving executives with little choice but to pass those expenses on to consumers.

This volatility is creating a stark divide within corporate America. Tech giants and financial institutions with massive cash piles remain largely insulated from these shifts. However, capital intensive industries such as automotive parts and logistics are feeling the heat intensely. In suburban Detroit, Lucerne International was forced to cancel plans for a fifty million dollar forging plant after tariffs tore holes in their global supply chain. Other firms haven’t fared as well; Spanish supplier Grupo Antolin recently filed for bankruptcy protection in the United States, explicitly citing energy costs and trade barriers as catalysts for their collapse.

Even retail titans aren’t entirely immune to the chaos. Executives at Home Depot have noted that any benefits gained from tariff refunds are being completely wiped out by the rising cost of energy and materials. As CEOs across various sectors report raising prices faster than they have in decades, there is a growing sense of uncertainty about where the ceiling actually sits. Until borrowing costs stabilize or supply chains find a new equilibrium, many American manufacturers fear they are simply fighting a losing battle against forces beyond their control.
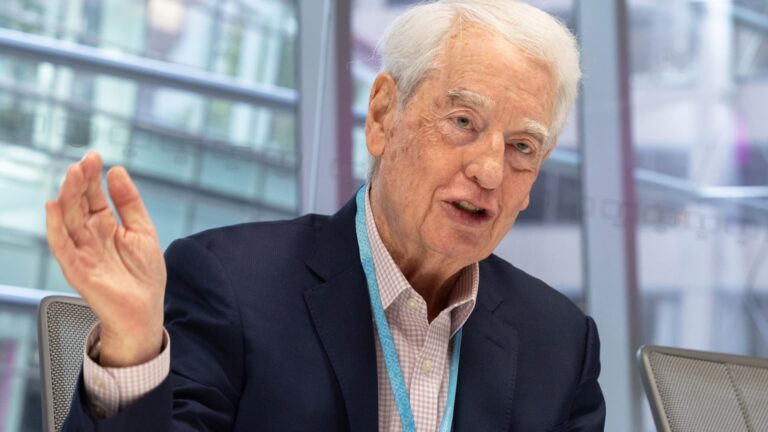
For decades, Bill Franke built a global aviation empire by mastering the art of the bargain. As the co-founder of Indigo Partners and chairman of Frontier Airlines, Franke became the architect of the ultra-low-cost model, making a fortune by stripping away every possible luxury and charging passengers for everything from carry-on bags to specific seat assignments. In the past, he famously dismissed travelers who expected free amenities as spoiled brats, arguing that those seeking comfort should pay for it rather than expecting the airline to absorb the cost.

However, times are changing, and so is Franke’s philosophy. The 89-year-old industry veteran has revealed that Frontier plans to introduce first-class seats on its Airbus fleet next year and is integrating SpaceX’s Starlink Wi-Fi into its cabins. While he insists these aren’t meant to rival the opulence of high-end international carriers like Singapore Airlines, he admits that providing consumers with an upscale option is now a strategic necessity. This pivot comes as the rigid budget model faces a harsh reality check driven by soaring pilot salaries, rising maintenance costs, and a massive surge in demand for premium travel experiences.

The shift is also a response to how the broader market has evolved. Major players like United and Delta have effectively weaponized Franke’s own playbook, introducing their own bare-bones economy fares while simultaneously expanding their luxury suites. With traditional giants adopting low-cost tactics at the bottom end of the market, budget carriers can no longer rely solely on being the cheapest ticket in town to survive. The collapse of Spirit Airlines earlier this year served as a stark reminder that simply running lean may not be enough to ensure sustainability in a volatile economic climate marked by fluctuating fuel prices and post-pandemic shifts in passenger behavior.

Despite these concessions toward comfort, Franke maintains that price remains the primary driver for many travelers, particularly younger flyers and middle-class families. He views these additions not as an abandonment of his principles but as necessary adjustments to stay competitive within a mature US market. While he believes such luxuries might still be unnecessary in emerging markets like Peru or Hungary, he acknowledges that fighting for survival in America requires a more flexible approach to what happens inside the cabin.

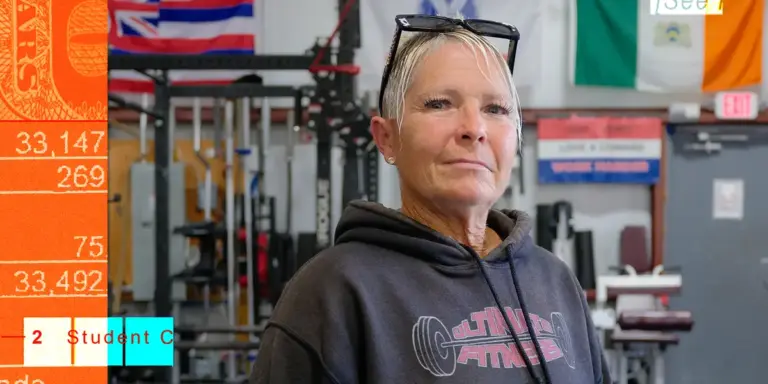
Nansi Lynch spent nearly three decades working as a school bus driver, balancing her mornings and evenings with running a gym she co owns with her son. While she never attended college herself, she wanted to ensure her children had every opportunity to succeed in the workforce. To make that happen, she took out federal parent PLUS loans to fund their degrees. Now 60 years old and eyeing retirement, Lynch finds herself trapped by a staggering 156,000 dollar balance that shows no sign of disappearing.

The financial burden is compounded by an interest rate of over nine percent, one of the highest available for federal loans. Because Lynch relied on income driven repayment plans and periodic deferments during gaps in employment, interest continued to pile up behind the scenes. This created a cycle where the total owed grew far beyond what she originally borrowed. With an annual salary of around 45,000 dollars from her driving job, the weight of six figure debt has become an insurmountable wall between her and the retirement she hoped to enter within five years.

Beyond the monthly payments, the debt has crippled Lynch’s ability to grow her small business. When she applied for a Small Business Administration loan to move her gym to a better location, the request was denied specifically because her debt load was already too high. Despite these hardships, Lynch refuses to let her children help with the payments, noting that they are already struggling with their own bills in a difficult economy. She would rather continue working well into her sixties or seventies than pass the financial burden back onto the very people she sacrificed for.

Looking back, Lynch says she does not regret providing an education for her children but warns others about the dangers of uncapped borrowing. She describes the current system as broken, pointing to recent graduates at her gym who hold expensive degrees yet cannot find stable employment. For Lynch, the lesson is a painful one about the true cost of parental sacrifice in an era of skyrocketing tuition and predatory interest rates that can follow a borrower long after their children have graduated.

For many American workers, hitting sixty feels like entering a precarious dead zone where they are viewed as too old to hire but remain far too young to retire. This gap is often exacerbated by the timing of government benefits, with Social Security typically unavailable until age 62 and Medicare not kicking in until 65. For those caught in the middle, a sudden layoff can trigger a crisis of confidence and financial stability, leaving seasoned professionals wondering why their decades of experience are suddenly seen as a liability rather than an asset.

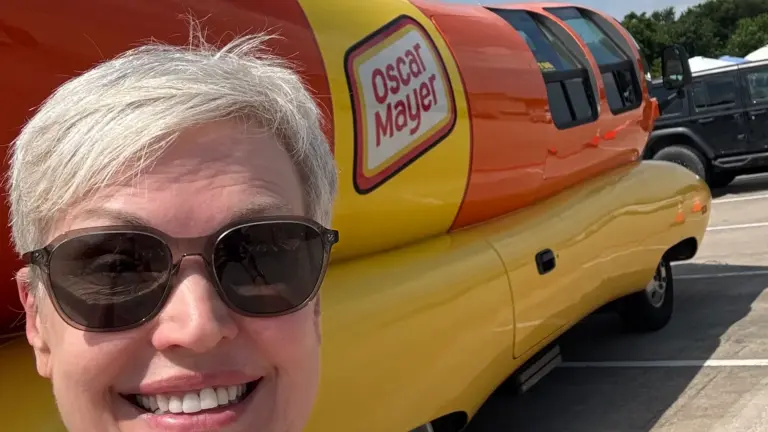
Cynthia Hennessy experienced this firsthand after being laid off from her corporate law position at age 61 following a company reorganization. Despite twenty five years of service, she found herself struggling against an invisible age ceiling, famously sharing her frustration on social media after being rejected for a job driving the Oscar Mayer Wienermobile because the company preferred recent college graduates. While Hennessy eventually found fulfillment in a lower paying role at the Make A Wish Foundation, her journey highlights the psychological toll of late career unemployment and the feeling that one has become obsolete in the eyes of recruiters.

Other workers have responded to this systemic bias by abandoning the corporate world entirely to reclaim control over their livelihoods. Todd Fannin, who faced a cycle of downsizing and relocations throughout his fifties while working in insurance, reached a breaking point at age 61. Rather than risk another layoff, he and his wife invested three hundred thousand dollars from their retirement savings to open an outdoor living franchise in Georgia. It was a gamble born out of necessity, driven by the desire to build an asset they owned rather than relying on an employer who might see them as expendable due to their age.

Some have managed to turn these professional crises into unexpected second acts through sheer persistence and pivot strategies. Margaret Bowles found herself unemployed as an attorney during the Great Recession at age 60, sending out thousands of resumes without response. Out of desperation, she leaned into her passion for sports photography, transforming a weekend hobby into a full time career shooting for major outlets like the Associated Press and covering NFL games. While these success stories offer hope, they underscore a harsh reality for aging Americans whose skills remain sharp even as their opportunities shrink within traditional employment structures.

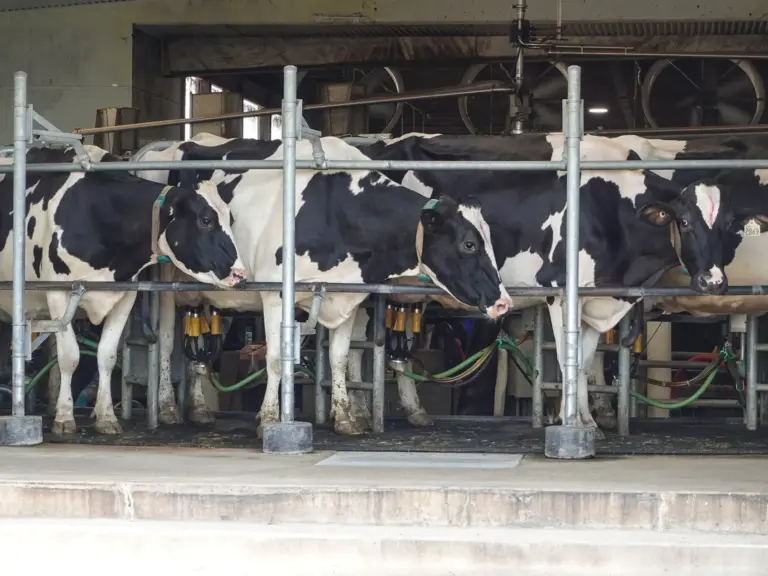
For Casey Pruim, running a dairy farm in Abbotsford, British Columbia, is a game of precision and timing. Every two days, 28,000 litres of raw milk leave his property to enter a complex distribution network designed on the belief that there will always be a buyer. However, that stability has vanished following the implementation of a fifty percent tariff by U.S. President Donald Trump on twenty billion dollars worth of Canadian goods. While much of Pruim’s milk stays within Canada, the sudden freeze in American sales has sent ripples through the provincial marketing system, leaving farmers wondering where their surplus will go.

The unique nature of dairy farming makes these trade tensions particularly volatile. Because cows cannot simply be turned off like a faucet, farmers face a harrowing dilemma when processors lose their export markets due to being priced out by tariffs. If the demand drops sharply, producers may be forced to dump fresh milk or take the drastic step of reducing their herds. Dylan Kruger from BC Dairy noted that while it is too early to determine if new international markets can mitigate the losses, the atmosphere remains one of profound uncertainty and instability for family businesses across the province.

This conflict stems from long standing disputes over Canada’s supply management system, which uses production quotas and import controls to stabilize prices for local farmers. Washington has characterized this system as protectionist and unfair to American producers, leading President Trump to claim via social media that Canada has been ripping off the United States for years. Canadian officials strongly reject this narrative, pointing out that despite current tensions, Canada actually runs a significant dairy trade deficit with its southern neighbor and provides substantial tariff free access to U.S. imports under existing agreements.

Economists warn that the immediate shock of losing such a massive market is nearly impossible to absorb quickly because profit margins are thin and alternative buyers do not appear overnight. Bryan Yu of Central 1 credit union suggested that while Canadian consumers might temporarily soak up some extra supply, there will likely be short term pain for many producers navigating these uncharted waters. Meanwhile, Prime Minister Mark Carney has signaled that Canada will not back down, implementing retaliatory tariffs on billions of dollars in U.S. goods as part of an effort to build economic resilience against aggressive foreign trade policies.

President Donald Trump has engaged in a level of stock market activity that dwarfs the collective trading of the entire United States Congress. A recent Bloomberg analysis reveals that since returning to office, the president has executed approximately 28,700 securities trades over a seventeen month period, averaging around 80 transactions every single market day. This represents a sharp departure from his first term, where his financial disclosures focused primarily on private businesses and real estate. His current portfolio includes hundreds of millions of dollars in municipal and corporate bonds, along with various bank securities and exchange traded funds.

Legal experts are sounding alarms over these findings, noting that this behavior breaks long standing presidential norms. Richard Painter, a former White House ethics lawyer and current securities law professor at the University of Minnesota, suggests this creates a massive ethical problem because presidents typically utilize blind trusts or stick to simple treasury holdings to avoid conflicts of interest. While the White House claims the assets are managed by independent third parties using computer models that replicate indexes, contradictions have emerged regarding whether the accounts are actually overseen by the president’s children.

Critics point to several highly suspicious timings within the filings that suggest potential overlaps between policy decisions and profit. For instance, records show the account purchased energy stocks shortly after tensions rose involving Iran and invested heavily in the nation’s largest egg producer during a widespread shortage before selling for a significant gain. Other trades involved hyperscaler stocks sold immediately following leaks about chip tariffs and investments in DoorDash right around a high profile delivery event at the White House.

This flurry of activity highlights a glaring gap in federal law, as most executive branch officials are barred from participating in government matters that affect their personal finances, yet the president remains exempt from those specific criminal statutes. While Trump has publicly endorsed bans on congressional stock trading to prevent corruption, he has aggressively pushed back against efforts to extend similar restrictions to himself and the vice president. To observers like Painter, the risk is systemic; if a leader profits personally from geopolitical volatility or economic shifts they help trigger, it undermines public trust in every decision made from the Oval Office.

Wall Street has spent the last year cheering a wave of upbeat earnings driven largely by the relentless march of artificial intelligence, but experts warn that this momentum may be hiding some structural weaknesses. According to Ben Snider, the chief US equity strategist at Goldman Sachs, the massive capital expenditure boom in AI has acted as a powerful engine for the S&P 500, accounting for nearly half of its earnings growth this year. However, Snider suggests that this specific tailwind is likely to fade starting next year, regardless of whether companies continue to pour money into AI infrastructure.

The concern is not necessarily that an AI bubble is about to burst in a dramatic crash, but rather that the current pace of growth is unsustainable. A significant portion of the market’s success has relied on semiconductor companies enjoying astronomical profit margins due to skyrocketing demand and limited supply. As supply chains stabilize and potential price corrections hit chips, those margins could shrink, leaving overall index earnings vulnerable. If the cost of hardware drops or investment slows slightly, the very sector that propelled the market forward could become a source of disappointment for investors.

Adding to this fragility is a less visible contributor to Big Tech’s bottom line: gains from private investments. These paper profits have padded earnings reports without generating actual cash flow, creating an illusion of strength that may vanish soon. Snider warns that removing this other income could create a substantial drag on S&P 500 earnings growth by 2027 compared to previous years. While the long term promise of AI remains intact, the immediate financial numbers suggest that the easy wins provided by initial infrastructure spending are coming to an end.

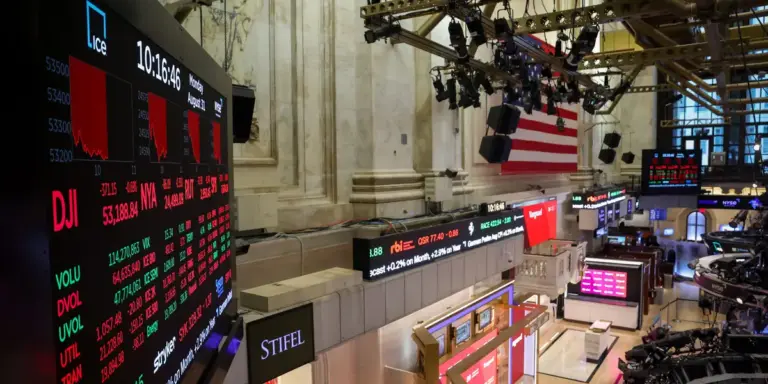
Investors faced a turbulent stretch last week as two distinct but powerful forces collided to shake confidence in the equity markets. The primary driver was a renewed anxiety over interest rates, with traders grappling with signals that borrowing costs may remain elevated longer than previously hoped. This shift created an immediate drag on valuations, particularly for growth stocks that are sensitive to the cost of capital, leading to widespread volatility across major indices.

Adding fuel to the fire were growing concerns regarding the long term viability and ethical guardrails of artificial intelligence. While AI has been the engine driving much of the recent bull market, new debates surrounding safety protocols and regulatory hurdles began to weigh on big tech shares. Analysts noted that while the enthusiasm for generative AI remains high, investors are starting to question whether the rapid pace of development has outstripped the industry’s ability to manage systemic risks.

The combination of macroeconomic pressure and sector specific fear turned what could have been a routine trading period into a genuine stress test for portfolios. Many market participants spent the week balancing their optimism about technological breakthroughs against the harsh reality of central bank policy. As it stands, the market appears to be searching for a new equilibrium where innovation can coexist with higher rates without triggering another significant correction.

The stock market is showing signs of renewed energy as several high profile companies approach critical buy zones, with retail trading giant Robinhood leading the charge. Shares of the platform surged recently after a series of favorable regulatory updates from both the SEC and the CFTC provided investors with much needed clarity. The rally pushed the stock above its designated buy zone on Friday, signaling potential momentum for those looking to enter positions in the digital brokerage space.

Meanwhile, eyes are turning toward SpaceX as it maintains a strong orbit around its own key pricing levels. The company received a massive boost late last week after securing a NASA contract valued at nearly one billion dollars. While the business continues to dominate headlines with its aerospace achievements, traders are closely watching as the stock tests an aggressive early entry point just above its initial IPO debut price.

Beyond these two heavy hitters, other names like ELF Beauty and Targa Resources have entered the spotlight as analysts scout for emerging trends. These movements come during a mixed period for the broader market, which has been grappling with post Federal Reserve volatility and shifting geopolitical dynamics between Washington and Beijing. Despite the noise, selective growth stocks continue to find support through strong fundamentals and strategic wins.

Investors are closely watching the horizon as a promising buy signal emerges for one of 2026’s most anticipated stocks, raising questions about whether the broader market is finally ready to take flight. While optimism is building around specific high growth opportunities, the current landscape remains fragmented. Recent trading sessions have seen a tug of war between different sectors, leaving many traders wondering if we are seeing a genuine recovery or simply another period of volatile rotation.

The latest data shows a mixed bag across the major indices. While the Nasdaq has managed modest gains driven by shifts within growth stocks, other benchmarks are struggling to find their footing. Both the Dow Jones and the small cap Russell 2000 recently slid to three month lows, suggesting that while big tech might be resilient, smaller companies and traditional industrial giants are feeling more pressure from macroeconomic headwinds.

Adding to the tension is the behavior of government bonds, with the 10 year Treasury yield holding steady at five percent. This level continues to act as a gravity well for equities, forcing investors to be far more selective about where they park their capital. With eyes now turning toward upcoming diplomatic meetings and Federal Reserve policy adjustments, the market seems to be in a cautious waiting game.

Despite these hurdles, analysts suggest that certain individual breakouts could lead the way forward. For those tracking potential winners into late 2026, this new buy signal represents a possible pivot point. If this leading indicator holds true, it may provide the spark needed to lift the wider indexes out of their recent slump and ignite a fresh rally across diversified portfolios.