Archive

November 14, 2026

Browsing

Investors who rely on AT&T for steady income are facing a challenging landscape as recent inflation data comes in hotter than expected. While retirees often hold the stock specifically for its quarterly payouts, a spike in consumer prices creates a ripple effect that can erode the actual value of those holdings. With October’s inflation report exceeding expectations, markets are bracing for potentially higher interest rate hikes from the Federal Reserve, putting immediate pressure on companies burdened by significant debt.

For AT&T, the danger lies in the relationship between treasury yields and dividend attractiveness. As the ten year Treasury yield climbs, government bonds become more appealing because they offer competitive returns without the corporate risks associated with wireless price wars or massive debt loads. Currently carrying nearly 150 billion dollars in net debt following its spectrum deals, AT&T faces higher costs every time it needs to refinance, making it vulnerable during periods of monetary tightening.

Looking at historical precedents provides a sobering perspective on potential losses. During the financial crisis of 2008 and 2009, AT&T saw its share price plummet by roughly 45 percent. For a large scale investor, such a drop could mean losing tens of thousands of dollars in principal even while continuing to collect dividends. This volatility highlights the importance of position sizing; experts suggest keeping individual income stocks to a small percentage of a total portfolio so that a severe downturn remains survivable rather than catastrophic.

Despite these macro pressures, the company’s core business fundamentals remain relatively stable. Revenue continues to grow and free cash flow currently covers dividend payments comfortably. However, looming competition from satellite services like SpaceX and general economic strain on consumers could squeeze margins further. Rather than reacting impulsively to a single inflation report, seasoned investors are encouraged to focus on their overall income strategy and monitor key indicators like upcoming Fed meetings and future dividend declarations before making drastic moves.
While global headlines remain fixated on geopolitical tensions and immediate inflationary pressures, a quieter threat is beginning to emerge on the horizon for investors. Financial forecasters are warning that the powerful engine driving the current stock market rally, namely explosive corporate earnings growth, may be running out of steam. Many analysts believe that by 2027, the market will face a significant deceleration in profits as the initial gold rush of artificial intelligence investments begins to level off.

The numbers tell a story of extreme highs followed by a projected cooling period. Current S&P 500 earnings growth has been stellar, comfortably outpacing historical averages and leading some to worry that we are living through an earnings bubble. However, projections from firms like Goldman Sachs suggest a steep drop ahead, predicting that growth could plummet from a robust thirty six percent in 2026 to just eleven percent by 2027. This anticipated slump is largely tied to a predicted slowdown in capital expenditures from big tech giants who have spent hundreds of billions building out AI infrastructure.

Adding to the anxiety is the reality that these massive investments carry heavy price tags. As interest expenses rise and the cost of capital remains elevated, the sheer expense of maintaining an AI ecosystem could eat into bottom lines. Strategists at Raymond James and Ned Davis Research have echoed these concerns, noting that it is becoming harder for companies to beat analyst expectations compared to previous quarters. There is a growing sense that the optimism surrounding AI might have been overdone, leaving equity valuations vulnerable if actual profit growth fails to keep pace with investor hopes.

Despite these warnings, most experts don’t expect an immediate crash but rather a shift toward higher volatility. The market is already attempting to price in this slower trajectory, creating a tug of war between those who fear underinvestment in data centers and those worried about wasteful spending. While stocks may continue to climb in the short term, the road toward 2027 looks increasingly bumpy as the era of easy gains fueled by AI hype gives way to a more disciplined financial reality.

While much of the tech sector has spent the last few weeks sliding away from record highs, Apple is managing to swim against the current. In a landscape where Big Tech firms are pouring trillions into artificial intelligence, investors are rewarding Apple for taking a far more conservative approach. Rather than gambling hundreds of billions on building its own massive infrastructure, Apple has opted to lean on existing partnerships, integrating tools like Google Gemini into Siri. By paying for access rather than funding an endless arms race of computing power, Apple appears to be avoiding the reckless spending sprees that are currently spooking Wall Street.

Beyond its disciplined approach to AI, Apple is benefiting from a genuine rebound in its core business performance. After several stagnant years where revenue growth barely kept pace with inflation, the company has returned to double digit quarterly growth. This fundamental improvement has made the stock a safe harbor for those fleeing more volatile sectors, positioning Apple as a stable alternative in an otherwise chaotic market environment.

However, this flight to safety may have pushed Apple’s price beyond reasonable limits. Because so many investors have piled into the stock as a hedge, its valuation has climbed to levels not seen in nearly twenty years. When compared to high growth giants like Nvidia, which continues to expand rapidly while trading at a relatively modest multiple of earnings, Apple looks increasingly overpriced despite its stability.

This creates a delicate balancing act for shareholders moving forward. If markets remain skeptical of AI spending, Apple will likely continue to shine as the prudent choice. But if investor appetite shifts back toward aggressive AI plays, there is a real risk that traders will sell off their expensive Apple shares to fund new bets elsewhere. What looks like strength today could easily become a liability if the wind changes direction once again.

The semiconductor giant Nvidia is facing a historic downturn as its stock plummeted for the sixth consecutive week, marking its worst losing streak since 2012. This downward spiral has wiped approximately 1.7 trillion dollars from the company’s market capitalization, causing it to lose its crown as the world’s most valuable firm to Apple. While investor sentiment had already begun to sour recently, the selloff accelerated sharply following a series of personal scandals involving longtime leader Jensen Huang.

The turmoil reached a breaking point on Thursday when Huang resigned as CEO after reports surfaced regarding two extramarital affairs, including one with an employee and another with an alleged Chinese spy. Following a frantic board meeting sparked by revelations in The New York Times, the company appointed Chief Financial Officer Colette Kress as interim CEO. The sudden exit of the co-founder, who had become a prominent figure in both tech and political circles under President Donald Trump, left shareholders reeling and caused shares to dive 13 percent this week alone.

Beyond the leadership crisis, broader economic and political headwinds have compounded the losses. Recent midterm election results saw Democratic victories that may lead to regulations slowing the rapid expansion of artificial intelligence infrastructure. Additionally, persistent concerns over rising interest rates have pressured the wider AI sector, particularly affecting those debt-reliant customers who fuel Nvidia’s massive demand. Together, these factors created a perfect storm that erased nearly 30 percent of the company’s value during this recent slump.

Attention now shifts to Colette Kress as she prepares to steer the company through its upcoming quarterly earnings report on Tuesday. Although analysts expect staggering revenue growth—projecting figures around 108.9 billion dollars—there is widespread skepticism about whether financial strength can outweigh the current instability. Industry experts warn that while the fundamentals remain strong, the shadow cast by Huang’s departure will likely keep investors cautious for several months to come.

Many investors believe they are safe from the volatility of individual stocks if they avoid buying shares directly, but the recent collapse of Nvidia proves otherwise. Because the chipmaking giant is a massive component of major benchmarks like the S&P 500 and the Nasdaq 100, its fortunes are inextricably linked to millions of employer sponsored retirement plans. With nearly 97 percent of retirement plans now offering index funds, most workers find themselves indirectly exposed to Nvidia regardless of whether they ever intentionally invested in the company.

The current crisis was sparked by shocking revelations regarding cofounder Jensen Huang, whose resignation as CEO followed reports of an extramarital affair with a suspected Chinese spy. This leadership vacuum sent shockwaves through the market, erasing more than 550 billion dollars in company value in just one week. For those holding broad ETFs like SPY or VOO, this dip creates a tangible drag on their balances since Nvidia makes up roughly six percent of the S&P 500, ranking it as one of the index’s largest holdings.

Financial experts warn that this situation exposes a fragile reality within the Magnificent Seven tech giants. Professor Shiva Rajgopal of Columbia Business School notes that while these companies create immense wealth, they often rely heavily on charismatic leaders who become synonymous with the brand’s success. When a figurehead like Huang falls, the fallout spills over rapidly into the stock price, reminding investors that extreme growth often comes with concentrated risk.

Despite the drama, there is a silver lining for those using diversified strategies. Even with Nvidia’s steep decline, the S&P 500 actually posted a weekly gain thanks to strength in other sectors. Experts suggest that instead of panic selling during temporary fluctuations, investors should trust the fundamental purpose of diversification. Since Nvidia’s hardware remains essential to the global AI infrastructure, many analysts argue that the long term value lies in the technology itself rather than any single executive’s tenure.

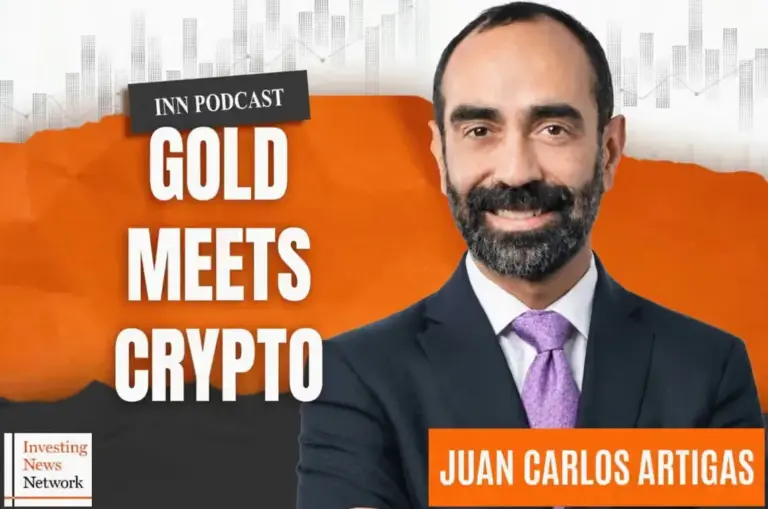
The dream of owning gold has traditionally involved heavy safes or secure bank vaults, but a new wave of digitalization is attempting to put the precious metal directly onto smartphones. Juan Carlos Artigas, the World Gold Council’s Americas CEO and global head of research, recently discussed the immense potential and lingering obstacles facing this shift during a conversation with the Investing News Network. While the idea of managing assets via an app offers unprecedented convenience, Artigas suggests that ease of access alone may not be enough to convince a skeptical public to move away from tangible holdings.

Current data highlights just how much room there is for growth in this niche. A collaborative report between the World Gold Council and Boston Consulting Group estimates the current digital gold market sits between 45 billion and 55 billion dollars. When placed next to the staggering 13 trillion dollars held in physical investments, the disparity is clear. However, experts believe that resolving key industry hurdles could unlock as much as 700 billion dollars in untapped demand, signaling a massive window of opportunity for platforms that can prove their reliability.

Despite the financial promise, moving toward tokens requires overcoming significant psychological and technical barriers. Even when a digital asset represents actual vaulted gold, users remain wary of cybersecurity threats and systemic failures. Artigas notes that while some investors are drawn to modern perks like easier collateralization and lending options, many still prioritize the ability to physically redeem their gold. For these traditionalists, a screen cannot replace the security of holding a coin or bar in their hand.

As digital gold evolves, it remains unclear whether it will eventually dominate the market or simply exist as another tool alongside exchange traded funds and physical bullion. The path forward depends largely on trust and transparency. According to Artigas, prospective investors must look beyond user interfaces and ask critical questions about how their assets are stored and verified before committing their capital to a virtual vault.

Barrick Mining has taken a significant step forward in its strategic restructuring by officially naming its North American spinoff American Barrick Gold. The company revealed on Tuesday that it has filed a registration statement with the U.S. Securities and Exchange Commission to pursue an initial public offering on the New York Stock Exchange, where it intends to trade under the ticker ABGC. A powerhouse group of financial institutions including Goldman Sachs, BofA Securities, Citigroup, and RBC Capital Markets will handle the distribution of the preliminary prospectus to investors.

While the official filing marks a milestone, potential shareholders will have to be patient regarding specific details. Barrick has not yet disclosed a definitive pricing strategy or a strict timeline for the debut, though previous guidance suggested the process could stretch toward the end of 2026. There is also some lingering ambiguity surrounding exactly which assets will fall under the new banner and what percentage of ownership will be offered to the public, although early indications suggest Barrick may retain a controlling majority stake.

The path to this IPO was not without friction, particularly involving industry giant Newmont. The two partners previously clashed over the diversion of joint venture resources toward the Fourmile discovery in Nevada, leading Newmont to attempt to block the spinoff entirely. That dispute was settled in August through a deal worth nearly two billion dollars paid to Barrick, resulting in Fourmile being integrated into Nevada Gold Mines rather than remaining a standalone asset within the spin-off structure.

This corporate maneuver comes at a time of strong financial momentum for Barrick. Recent quarterly reports show a dramatic surge in free cash flow, which jumped from 141 million dollars in the second quarter to 642 million dollars in the third. This growth was driven largely by increased production at sites like Cortez and Carlin, along with steady output from operations in Mali. Chief Executive Mark Hill noted that these results represent a full year of consistency as the company works to restore its reputation for operational discipline and excellence.

Altius Minerals is significantly broadening its reach into the critical metals sector with a deal to acquire TNR Gold. This move allows the company to secure key royalties tied to major operations in Argentina, specifically focusing on copper and lithium. By absorbing TNR Gold, Altius gains access to the promising Los Azules copper project managed by McEwen Copper and the active Mariana lithium brine operation run by Ganfeng Lithium.

The acquisition values the junior firm at approximately 122 million US dollars, representing a substantial sixty percent premium over its recent trading price. Under the terms of the agreement, TNR shareholders will receive a combination of Altius shares and stakes in a newly created entity called TNR SpinCo. This spin off is designed to house the Shotgun gold project located in Alaska, ensuring that while Altius pivots toward battery metals, the Alaskan asset remains distinct although Altius will maintain a minority ownership stake and a small royalty there.

Looking ahead, the timing of these acquisitions aligns with aggressive growth targets for the underlying projects. The Los Azules site is eyeing a final investment decision by mid 2027 with hopes of starting production by 2030, potentially delivering massive amounts of copper cathode annually for two decades. Meanwhile, the Mariana project is already operational and currently scaling up its lithium carbonate output, providing Altius with immediate exposure to an operating stage asset during a period of high demand for energy transition minerals.

This deal comes amidst a broader wave of consolidation across the mining industry throughout 2026. From multi billion dollar mergers in North America to strategic shifts in Australia, companies are increasingly rearranging their portfolios to maximize efficiency and resource security. For Altius, this latest transaction reinforces its strategy of diversifying away from traditional assets and leaning heavily into the materials essential for global electrification.

Anthropic, the creator of the Claude AI model, is preparing for a historic entry into the public market with a planned Nasdaq listing that could become the second largest initial public offering ever recorded. The company intends to sell 825 million Class A shares priced between 70 and 78 dollars each, a move that could raise approximately 64.4 billion dollars at the high end of its range. This ambitious debut suggests a staggering valuation reaching up to 1.4 trillion dollars, signaling immense investor confidence in pure play artificial intelligence firms.

Interest in the offering appears overwhelming, with reports indicating that order demand has already exceeded the available shares several times over. Leading the charge are heavyweights like Goldman Sachs and Morgan Stanley, while industry titans including Nvidia, Google, and Microsoft are reportedly planning to pour an additional 26 billion dollars into a concurrent private placement. For many investors, this represents a rare opportunity to gain direct exposure to an AI lab without having to go through diversified tech conglomerates.

Despite the financial momentum, the road to trading on November 19 comes with significant caveats. While revenue surged to 17 billion dollars in the third quarter, Anthropic recently swung to an operating loss of 567 million dollars due to the skyrocketing costs of computing power. More strikingly, the company’s extensive prospectus includes nearly 100 pages of risk factors, candidly warning potential shareholders that its own models could potentially pose catastrophic or even existential risks to humanity.

Founded by former OpenAI employees as a public benefit corporation, Anthropic operates under a unique mandate that requires its leadership to weigh global safety alongside profits for shareholders. As it prepares to trade under the ticker ANT, all eyes will be on whether it can maintain its trajectory or suffer a similar fate to other massive debuts like SpaceX, whose shares dipped following their own blockbuster listing last June.

CME Group is moving closer to securing a landmark storage agreement that could fundamentally change how investors interact with the uranium market. According to reports from Bloomberg, the exchange operator is currently finalizing a deal with ConverDyn, a joint venture between Solstice Advanced Materials and General Atomics. This partnership would allow CME to store uranium concentrates at the Metropolis Works facility in Illinois, which stands as the only commercial scale conversion plant operating within the United States.

If finalized, the arrangement would pave the way for a futures contract based on physical yellowcake rather than simple cash settlements. Under the proposed framework, Solstice would oversee the inventory management while ConverDyn handles the necessary accounting. Legal teams are reportedly reviewing the documents now, with hopes that the deal can be closed before the end of the calendar year. While all involved parties have remained silent on the matter, such a move would provide a tangible alternative to current cash settled contracts that often suffer from low trading volume.

The timing of this initiative aligns with a broader surge in global demand for nuclear fuel, driven largely by government energy expansions and the massive electricity requirements of artificial intelligence data centers. With years of underinvestment leaving supply tight, spot prices have climbed significantly, recently hovering around ninety dollars per pound. By introducing physical delivery options, CME joins a small group of entities like the Sprott Physical Uranium Trust that offer direct exposure to the actual commodity.

This push into uranium is part of a wider aggressive expansion strategy by CME Group to diversify its product offerings throughout 2024. The exchange has already made waves this year by updating its gold and silver trading hours and announcing upcoming ventures into tungsten futures. By bridging the gap between financial speculation and physical ownership of radioactive fuel, CME aims to capture more of the momentum building behind the nuclear energy renaissance.