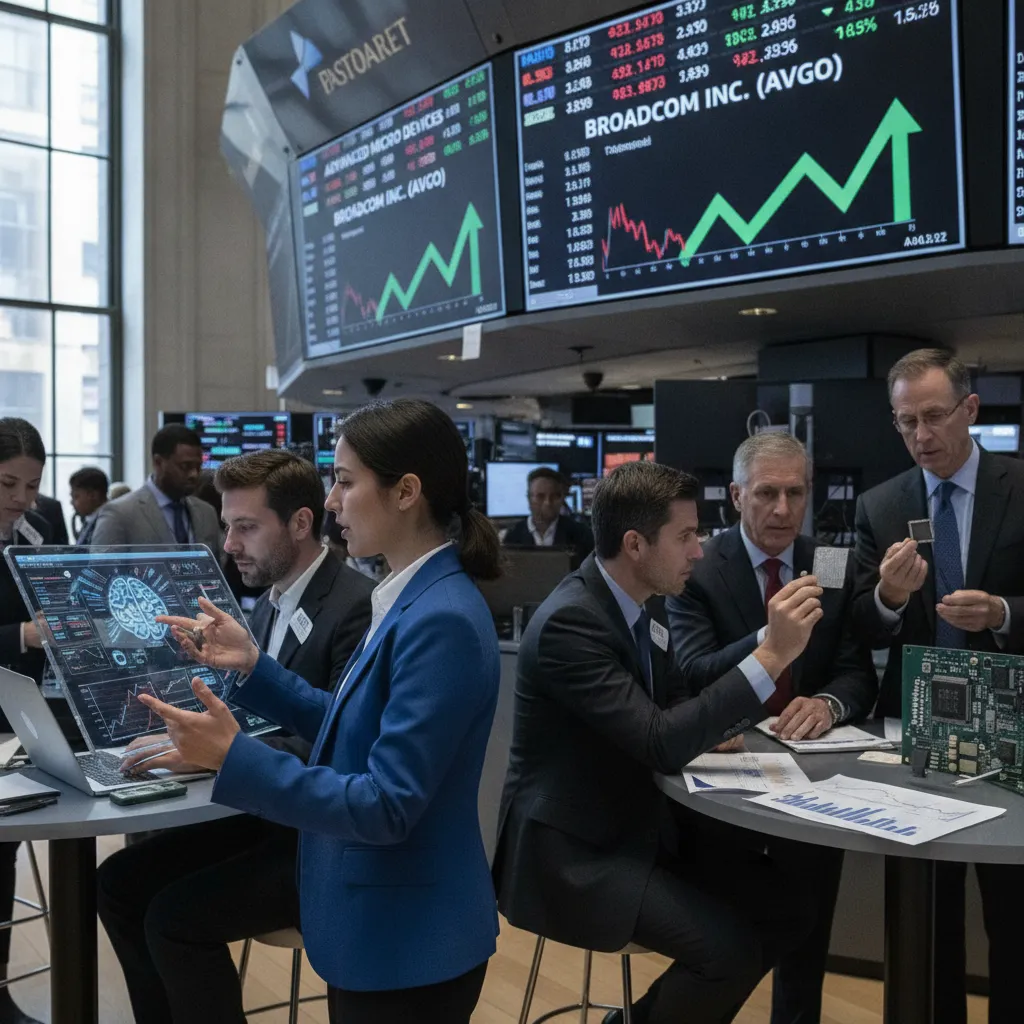
As the artificial intelligence gold rush continues to reshape the tech landscape, investors find themselves weighing the merits of two heavy hitters: Advanced Micro Devices and Broadcom. Both firms have ridden a massive wave of momentum, with AMD surging 421 percent and Broadcom climbing 285 percent over the last three years. While both remain essential players in the AI ecosystem, they offer very different paths to profit, leaving shareholders to decide whether versatility or specialization holds more value leading into 2030.
AMD is positioning itself as a primary beneficiary of the shift toward agentic AI, where autonomous systems require the robust power of central processing units to function efficiently. This strategic pivot is already paying dividends, evidenced by a staggering jump in data center sales and a widening gap between AMD and its longtime rival, Intel. With an estimated trillion dollar opportunity looming for its AI accelerators and GPUs, AMD represents a high growth play backed by aggressive expansion in market share.
On the other side of the ring, Broadcom is dominating the niche of application specific integrated circuits. By creating custom chips tailored for specific workloads, Broadcom provides big tech giants like Meta and Alphabet with energy efficient alternatives to general purpose GPUs. The numbers reflect this success, with AI semiconductor revenue skyrocketing and projections suggesting these figures will nearly double again within just a few years.
When choosing between the two for a long term hold through 2030, the decision often comes down to price tags rather than product specs. Despite AMD’s rapid earnings growth, it carries a steep valuation premium compared to Broadcom. Because Broadcom trades closer to the industry average for information technology stocks while maintaining massive scale and reliable corporate contracts, it emerges as the slightly more attractive option for those wary of overpaying for future growth. Regardless of which horse one bets on, both companies appear fundamentally locked into the infrastructure that will define the next decade of computing.
Comments are closed.