Archive

October 26, 2026

Browsing

Serial entrepreneur Marc Lore is attempting to redefine how Americans eat with Wonder, a vertically integrated food technology platform that bundles multiple restaurant concepts into single hubs. By leveraging his experience in e-commerce and a massive war chest of investments, Lore has scaled the company rapidly, reaching a pre-money valuation of 9 billion dollars. His strategy relies on removing the friction of traditional delivery through the acquisition of Grubhub, allowing Wonder to bypass typical commission fees and offer high quality meals at prices intended to compete with grocery deliveries.

The company is currently eyeing an aggressive expansion into Texas, aiming to launch at least 100 locations across the state by late 2027. Unlike traditional eateries, Wonder utilizes electric storefronts that require no gas or venting, enabling them to set up shop quickly in urban and rural areas alike. These sites act as curated food halls featuring everything from celebrity chef creations to acquired cult favorites, all prepared via centralized commissary kitchens and finished locally for maximum efficiency.

Automation is central to Lore’s long term vision, with current systems already handling the assembly of bowls and salads. The ultimate goal is a fully autonomous preparation and delivery cycle by 2040. Beyond robotics, Lore is exploring innovative revenue streams including a subscription model that would allow users to essentially operate their own virtual restaurants within the ecosystem. This push toward scalability suggests a broader desire to capture markets in exurban regions where dining options are often limited to fast food chains.

As Wonder continues its ascent, Lore is signaling that an initial public offering may be on the horizon once market conditions stabilize. While he has remained vague on specific timing, he views going public as a way to secure the capital necessary for further mergers and acquisitions to build what he calls a generational business. Having previously exited ventures like Diapers.com and Jet.com for billions, Lore believes his formula of combining accessibility with cutting edge tech creates a moat that remains defensible even in an era dominated by artificial intelligence.
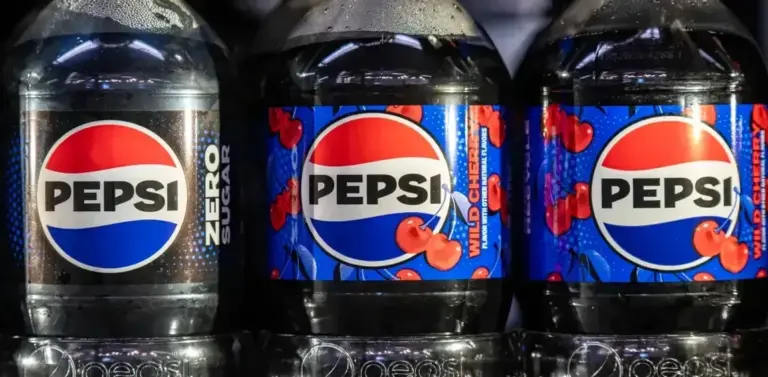
The loss of a longtime partner can often serve as a wake up call, and for PepsiCo, the departure of KFC feels particularly poignant. After four decades of association, including a period when Pepsi actually owned the fried chicken giant, KFC announced it will replace Pepsi products with Coca-Cola across its 3,700 U.S. locations this January. While the move represents only a small fraction of total sales, it serves as a visible symbol of the eroding brand power that has plagued the cola titan in recent years.

The gap between the two rivals has widened significantly since the era of flashy celebrity endorsements and high stakes taste tests. Once separated by only a few percentage points in market share, Pepsi now trails far behind Coke’s dominant lead. The slide reached a historic low in 2024 when Pepsi dropped to third place in the U.S. carbonated soft drink market, falling behind Dr Pepper for the first time ever. This decline highlights a strategic divergence where Coca-Cola focused intensely on brand innovation and lean operations while Pepsi evolved into a diversified conglomerate.

For years, PepsiCo executives essentially left their soda business on autopilot, distracted by the massive success of their Frito Lay snack division. Because chips and dips offered far higher profit margins than sugary drinks, investments flowed toward Doritos and Cheetos rather than promoting the flagship cola. This strategy worked as long as snack sales soared, but inflation has recently caused consumers to push back against rising chip prices, leaving the company vulnerable just as they realized their beverage wing had stagnated.

CEO Ramon Laguarta has openly admitted that the beverage side of the house requires urgent attention and renewed focus. To stem the tide, the company is looking to ramp up marketing spending and expand its portfolio through acquisitions like prebiotic soda maker Poppi. However, some activists believe these tweaks aren’t enough and are calling for a complete corporate divorce between the food and drink divisions to unlock hidden value and force a dedicated return to winning the cola wars.

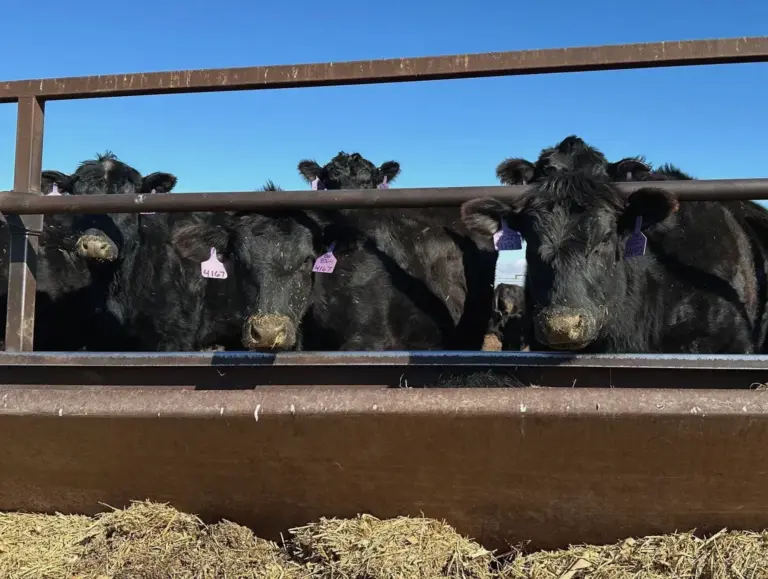
A recent decision by President Donald Trump to implement a ninety day pause on specific beef tariffs has sent shockwaves through the American heartland. While the move was designed to lower grocery bills for consumers by easing the flow of cheaper imports, primarily from Brazil, it has left many domestic producers feeling abandoned. Ranchers who were preparing to send their cattle to market saw auction prices plummet almost immediately, turning what should have been a profitable season into a period of financial instability.

The backlash has extended beyond individual farms to major industry advocates. Organizations including the National Cattlemen’s Beef Association and the Farm Bureau have voiced strong opposition, while several rural Republican lawmakers have found themselves distancing themselves from the administration’s stance. Despite this friction, it remains uncertain if these grievances will translate into a political shift during the upcoming midterms. Some ranchers admit frustration but suggest that broader support packages, such as billions in federal farm relief, may keep them loyal to the current administration.

Agricultural economists warn that this volatility does more than just hurt short term profits; it disrupts long term investment. David Anderson of Texas A&M University notes that higher prices earlier this year should have encouraged ranchers to expand their herds, which are already at their lowest levels since 1951. By making foreign imports cheaper, the government effectively muted those market signals, discouraging domestic growth at a time when stability is desperately needed.

Beyond politics and trade wars, the industry is fighting a losing battle against environmental stressors and rising overhead. Intense drought cycles driven by warming temperatures have increased feed costs, while geopolitical tensions have pushed up the price of fuel and fertilizer. This combination of erratic trade policy and harsh climate conditions creates a daunting landscape for the next generation, leaving many young heirs wondering if the grueling life of a rancher is still financially viable.

The glittering promise of an artificial intelligence revolution may be hitting a wall of reality for the average American corporation. According to a recent analysis from Torsten Slok, the chief economist at private equity powerhouse Apollo Global Management, the massive wave of investment pouring into AI has yet to translate into actual profits for companies operating outside the narrow confines of the tech sector.

To get a clear picture of the landscape, Slok examined what he calls the S&P 493, effectively stripping away the seven dominant tech giants like Nvidia, Microsoft, and Apple from the broader market index. His findings suggest that for these remaining hundreds of companies, both profit margins and revenue per employee have remained stubbornly flat. Despite the pervasive hype surrounding generative tools and automation, there is little to no empirical evidence that AI is currently driving meaningful productivity gains across general industry.

Slok remains skeptical that non-tech firms can easily replicate the success of their software-driven counterparts. He argues that while AI functions as an incredibly powerful calculator, it lacks the essential elements required to actually grow a business. In his view, true commercial success relies on judgment rather than raw data processing, noting that machines cannot grasp complex human concepts such as accountability, organizational culture, or ethical trade-offs.

Ultimately, this suggests a fundamental disconnect between technical capability and financial utility. Because AI struggles with trust and reputation management—factors that heavily influence long-term revenue growth—it may remain a sophisticated tool without becoming a primary engine for profitability. This perspective aligns with other recent studies indicating that the anticipated surge in global productivity has failed to materialize in real-world balance sheets.