Archive

October 2026

Browsing

Most drivers barely glance at the diesel pump during a fill up, feeling a sense of relief that their personal vehicle runs on gasoline. However, while only a tiny fraction of passenger cars rely on diesel, the vast majority of the American economy does. From massive semi trucks and freight trains to the combines harvesting corn in the Midwest, diesel is the essential workhorse fuel that keeps goods moving. As prices climb toward record highs due to geopolitical conflicts in the Middle East and Ukraine, these costs are beginning to trickle down into the wallets of everyday consumers who may never actually buy a gallon of the fuel themselves.

The impact is felt most acutely in the agricultural sector, where timing couldn’t be worse for farmers currently in the heat of the fall harvest. High octane operations like combine harvesting can consume hundreds of gallons of diesel daily, forcing some growers to dig out vintage equipment from decades ago just to save a few cents per acre. These increased production costs don’t stay on the farm; they migrate toward supermarkets and warehouse stores. While transportation typically accounts for a small percentage of a food item’s total cost, certain products are far more sensitive to fuel spikes than others.

Consumers will likely see the biggest price jumps on items that travel long distances or require constant cooling. Fresh produce shipped from California or Washington state must endure thousands of miles in refrigerated trucks that burn extra fuel just to keep perishables cold. Similarly, heavy but low value items such as bottled water, soda, and canned goods become significantly more expensive to move relative to their retail price. Beyond the grocery aisle, these surges manifest as higher home heating oil bills in the Northeast and creeping fuel surcharges on packages delivered by services like UPS.
Wall Street is buzzing with reports that Starbucks has been exploring a potential takeover of Chipotle Mexican Grill, a move that would unite two of America’s most dominant fast-casual forces. According to sources cited by the Financial Times, the coffee giant has spent recent months consulting with advisers on a proposal that could reshape the landscape of the restaurant industry. The news sparked an immediate reaction in the markets, sending Chipotle shares climbing while Starbucks saw a dip, reflecting a divide among investors over whether such a massive merger actually adds value.

Much of the speculation centers on Brian Niccol, the current CEO of Starbucks and former leader of Chipotle. Niccol famously steered the burrito chain through a devastating food safety crisis years ago, making him uniquely qualified to understand Chipotle’s internal mechanics. For Niccol, acquiring his former company could be a legacy-defining move, potentially transforming Starbucks into a multi-brand powerhouse similar to Yum Brands or Inspire Brands. Such diversification would protect shareholders by balancing coffee sales against mealtime traffic and provide Chipotle with an immediate roadmap for global expansion using Starbucks’ vast international infrastructure.

Beyond high-level strategy, there are practical reasons why these two brands might fit together. Analysts point out that nearly ninety percent of Chipotle locations sit within a mile of a Starbucks, suggesting huge opportunities for shared real estate development and streamlined corporate operations. There is also the possibility of merging their digital ecosystems into one massive loyalty program to capture more consumer spending across different times of day. Unlike previous owners like McDonald’s, who clashed with Chipotle over franchising models, Starbucks operates most of its stores directly, aligning better with Chipotle’s preferred way of doing business.

However, skeptics argue that this may be an ill-timed distraction for Niccol. He stepped into the role at Starbucks specifically to lead an embattled turnaround focused on restoring customer loyalty and improving service standards_a mission that is far from complete. Attempting to integrate another multibillion dollar company while still fixing his own house could prove risky. While some see a perfect synergy in caffeine and carnitas, others believe the probability of a deal closing remains low as Starbucks continues to prioritize its own recovery first.

A wave of selling swept through the semiconductor and cloud infrastructure sectors on Thursday as investors reacted to updated financial figures from OpenAI. Shares of industry heavyweights like Nvidia and Oracle took a hit, while specialized players such as CoreWeave saw even sharper declines. The volatility followed reports that OpenAI’s annualized revenue stood at approximately 50 billion dollars at the end of September, a figure significantly lower than the 68 billion dollar estimate that had circulated among traders just weeks prior.

While the discrepancy appears stark, sources suggest the difference stems from how partner revenues were calculated versus direct earnings. Despite the downward adjustment, OpenAI highlighted strong momentum within its internal metrics, boasting a total run rate growth of 77 percent in the third quarter and doubling down on its enterprise sector with 107 percent growth. However, these gains weren’t enough to soothe a broader market already sensitive to the massive valuations currently attached to generative AI firms.

The fallout extended beyond the immediate ecosystem, dragging down chipmakers including AMD, Broadcom, Intel, and Super Micro Computer. This collective dip underscores the precarious relationship between software developers and their hardware providers; any perceived slowdown in adoption or monetization at the top of the AI food chain sends ripples through every company providing the chips and servers required to power these models.

This financial scrutiny comes at a critical juncture for OpenAI as it navigates immense pressure to justify an 852 billion dollar valuation ahead of an anticipated IPO in 2027. The company is not alone in this struggle for legitimacy, as its primary rival Anthropic faces similar skepticism regarding its own astronomical valuation targets despite reporting staggering losses. Between regulatory hurdles and intensifying debates over AI safety—which recently led OpenAI to scrap plans for its GPT-6.1 Astra model—the path toward public markets remains fraught with uncertainty for both giants.

Wall Street is nursing a hangover today after an underwhelming revenue update from OpenAI cast a shadow over the once unstoppable artificial intelligence rally. U.S. stock futures remained largely flat on Thursday night, reflecting a cautious mood among traders following a sharp sell off in big tech. The turbulence began when reports surfaced that OpenAI’s annualized revenue sat at 50 billion dollars through September, falling short of the 68 billion dollar figure many investors had previously banked on.

The fallout was immediate and widespread across the semiconductor and infrastructure sectors. Heavyweights like Nvidia and AMD saw their shares slide, while CoreWeave and Oracle faced even steeper declines as the market questioned whether the AI boom was beginning to lose momentum. This volatility pushed the Nasdaq Composite to its steepest single day drop since mid August, erasing recent record highs and dragging the S&P 500 into a two day losing streak despite the Dow remaining relatively resilient.

Beyond the AI fray, another shockwave hit the telecommunications industry late Thursday. Shares of SpaceX ticked upward after announcing a deal to acquire a nationwide spectrum portfolio, a move seen as a major boost for Starlink Mobile’s capabilities. However, this victory for Elon Musk came at the expense of traditional carriers; AT&T, Verizon, and T-Mobile all suffered significant losses in extended trading as investors feared increased competition would eat into their established market shares.

Looking ahead, global markets remain on edge with Asia Pacific indices expecting a muted start due to these tech jitters combined with ongoing geopolitical tensions in the Middle East. Back home, domestic investors are keeping a close eye on upcoming consumer sentiment data and early earnings reports from Delta Air Lines to gauge where the broader economy stands amidst this sudden shift in tech optimism.

Wall Street is showing little appetite for David Ellison’s ambitious vision of a consolidated media powerhouse. Just two days into the massive merger between Skydance, Paramount, and Warner Bros. Discovery, shares of the newly formed Skydance Corp. continued to slide on Wednesday. Trading under the ticker SKYD, the stock dipped nearly 8 percent by midday, falling toward 8.78 dollars per share after already closing lower on Tuesday. It is a cold reception for a deal valued at 111 billion dollars that promised to reshape the entertainment landscape but has instead left investors twitchy.

The primary source of anxiety centers on a staggering mountain of debt totaling roughly 80 billion dollars inherited by the combined entity. While David Ellison and co-CEO Ynon Kreiz have attempted to soothe markets by mentioning a multiyear recovery plan, analysts aren’t buying it just yet. Experts point to a long history of failed mega-mergers in the media sector as reason for caution, fearing that integration hurdles and execution errors will outweigh any theoretical benefits of scale. This skepticism was echoed by Fitch Ratings, which downgraded the company’s credit rating shortly before the deal closed, citing extreme leverage and uncertainty over whether the firm can actually realize its projected cost savings.

Beyond the balance sheet, Skydance faces an uphill battle against systemic industry shifts. The company is grappling with declining traditional television revenues and a cutthroat streaming environment where success depends heavily on unpredictable hits. These structural pressures make an already precarious financial situation feel even more volatile to outside observers who worry that management may struggle to steer such a behemoth through current market headwinds.

Adding to the tension is a looming deadline next week regarding shareholder warrants. Hundreds of millions of these options allow certain stockholders to buy shares at 12 dollars apiece, but with the current stock price languishing well below that mark, those options are effectively underwater. Meanwhile, total control remains firmly in the hands of David Ellison, his father Larry Ellison, and RedBird Capital Partners via Class A voting shares, leaving public investors with limited influence over how this high-stakes gamble unfolds.

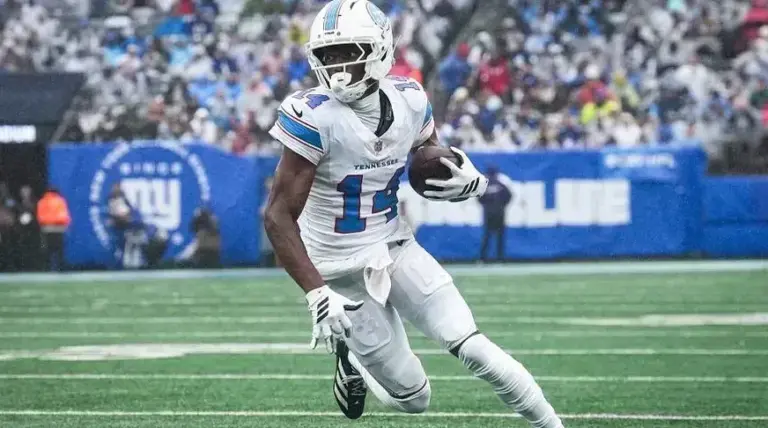
As we cross the threshold into week five of the season, the fantasy landscape for rookie receivers is beginning to shift in significant ways. While some newcomers have struggled to find their footing in complex offensive schemes, others are starting to emerge as reliable targets. The most notable riser right now is Tennessee Titans standout Carnell Tate, who has quickly turned heads with his ability to create separation and secure contested catches. His recent performance against the New York Giants served as a coming out party, proving that he can handle a heavy workload under pressure.

On the flip side, expectations have taken a hit for Chris Bell. After an initial burst of optimism during training camp and the first few outings, Bell has seen his production dip significantly over the last two weeks. He seems to be struggling with consistent routing and hasn’t yet established a rapport with his quarterback, leading many fantasy managers to question whether he will remain a viable starter or simply become a depth piece for the remainder of the year.

Beyond these two polar opposites, several other rookies are hovering in a state of uncertainty as they battle for snaps on the depth chart. This period of the season often acts as a filter where true talents separate themselves from those who were merely hyped heading into the draft. For owners holding onto high ceiling prospects, patience remains key, but current trends suggest that players like Tate are moving toward stardom while others may need a complete reset in their approach to survive the midseason slump.

The ambitious marriage of Paramount and Warner Bros. Discovery has hit a bumpy road immediately following its arrival on the New York Stock Exchange. Shares of the newly formed Skydance plummeted roughly seven percent during their second day of trading, marking a rocky start for a company that had already seen prices dip upon its Tuesday debut. While the closure of the merger represents a significant milestone and follows a favorable legal settlement with state attorneys general, investors seem less interested in the victory lap and more concerned with the balance sheet.

Wall Street is currently staring down a daunting eighty billion dollars in debt, leaving many analysts wary of the firm’s high leverage. The leadership team, led by Chairman and CEO David Ellison and co-CEO Ynon Kreiz, insists they can simultaneously slash costs and increase content spending to build a premier streaming powerhouse combining HBO Max and Paramount+. However, critics argue that this is essentially a show me story, noting that there is still precious little clarity regarding the final pricing strategies or organizational structure of this consolidated empire.

Some experts remain optimistic, pointing to the sheer volume of intellectual property and sports rights now under one roof as a recipe for success. Analysts like Matthew Condon suggest that if the company can effectively optimize its thirty billion dollar content budget, the current low stock price might actually represent a favorable risk reward opportunity. This bullish view depends entirely on flawless execution, assuming that existing business segments maintain their current trajectories while the company chases six billion dollars in projected cost synergies over the next few years.

Other observers are far more cautious, recalling previous media mergers where legacy cable assets evaporated faster than corporate efficiencies could be realized. With limited room to issue further debt after recent bond sales, any unexpected surge in subscriber churn or a slump in box office returns could leave Skydance without a safety net. As investors await third quarter earnings reports for concrete evidence of progress, the pressure remains firmly on Ellison and Kreiz to prove that their vision for a streamlined streaming giant isn’t just an exercise in optimism.

Micron Technology has entered a financial stratosphere that seemed unimaginable just a few years ago, with its stock climbing 485 percent over the past year. Now trading above 1,000 dollars per share and boasting a market valuation of 1.2 trillion dollars, the company finds itself in a position similar to peers like Nvidia and Broadcom, who both opted for ten-for-one stock splits earlier this year. For many retail observers, the skyrocketing price tag makes a split seem inevitable as a way to make individual shares feel more affordable to the average investor.

However, a closer look at Micron’s strategy suggests that management is prioritizing substance over optics. During a recent earnings call, leadership indicated that their primary goal for handling excess cash is not splitting the stock but rather aggressive share repurchases. While a split might attract momentum traders by lowering the barrier to entry, it does nothing to increase the actual value of the business. With most modern brokerages offering fractional shares, the psychological appeal of a lower share price has become less critical than it once was for small scale investors.

The drive toward buybacks is fueled by an unprecedented explosion in wealth driven by the artificial intelligence memory boom. Data centers requiring high bandwidth memory have sent Micron’s financials soaring, with fiscal 2026 revenue hitting 133.2 billion dollars and adjusted free cash flow jumping to an astonishing 62.3 billion dollars. This massive influx of liquidity provides the company with plenty of ammunition to reduce its total share count, which creates genuine long term value for shareholders in a way that a cosmetic split cannot.

Looking ahead, investors should focus less on whether the ticker symbol drops from four digits to two and more on how Chief Financial Officer Mark Murphy executes his plan for capital returns. With billions in net cash and expectations for even higher free cash flow in early 2027, Micron appears poised to leverage its treasury to reward holders directly. In an era of AI led hypergrowth, shrinking the number of outstanding shares may prove far more lucrative than simply changing the math on how those shares are divided.

Investors holding shares in Rocket Lab find themselves at a precarious crossroads where explosive growth meets a daunting valuation. On paper, the company’s trajectory looks impressive, boasting a sixty two percent increase in quarterly sales and a massive backlog of signed contracts totaling over two billion dollars. This pipeline includes significant government work, such as a nearly four hundred million dollar deal with the Space Force, suggesting that demand for their satellite services and launches remains robust.

Despite these gains, the financial reality is more complex because the company continues to lose money. Without consistent earnings to ground its stock price, analysts have turned to the price to sales ratio, which reveals that Rocket Lab is trading at over sixty times its annual revenue. For comparison, the broader S&P 500 typically trades around three times sales. This staggering gap suggests that current shareholders are essentially paying a premium for future success that hasn’t actually happened yet.

The pivot point for the entire investment thesis rests on Neutron, the company’s next generation rocket currently under development. Management has explicitly linked their first projected adjusted profit to the successful flight of this vehicle. Until then, Rocket Lab will continue to burn through cash, recording a negative free cash flow of over one hundred ten million dollars in just one quarter as they race toward the launch pad.

Timing has now become the primary risk factor for those holding RKLB stock. While leadership originally hoped for progress by year end, the window for an orbital flight before January is closing rapidly. If Neutron doesn’t fly until 2027, the promised path to profitability slides further away. Investors must now decide if they believe in the long term vision enough to weather another period of heavy spending or if the current hype has pushed the price too far ahead of reality.

Cenovus Energy is doubling down on its footprint in the Canadian oil sands, announcing a cash-and-stock agreement to acquire Athabasca Oil for roughly 5.7 billion Canadian dollars. The move comes as a strategic gamble that the federal government will deliver on promises to expedite a new Pacific pipeline, which would allow producers to bypass traditional bottlenecks and reach international markets more efficiently. By absorbing Athabasca, Cenovus immediately bolsters its thermal operations by about 45,000 barrels of oil equivalent per day, with ambitious plans to scale that figure up significantly by 2032.

The deal also cleans up corporate housekeeping for both parties by giving Cenovus full control of Duvernay Energy. Previously a joint venture between the two firms, the consolidated ownership should streamline development in the Kaybob Duvernay region, where leadership expects output to climb toward 20,000 barrels per day. For Athabasca shareholders, the windfall was immediate; stock prices jumped over 14 percent following the news that they would receive a combination of cash and equity valued at 12 dollars per share.

Timing is everything for this acquisition, arriving shortly after Prime Minister Mark Carney signaled that Ottawa would fast-track reviews for the proposed Pacific Link pipeline. This million-barrel-per-day project is seen as a vital lifeline for Canada to diversify its exports away from the United States during a period of heightened trade tension and tariff pressure. Cenovus CEO Jon McKenzie believes this increased capacity could allow the company to accelerate projects like Athabasca’s Corner site by several years.

However, the path forward isn’t without hurdles. While the production goals are aggressive, the federal government has tied pipeline approvals to strict mandates regarding carbon capture and storage technology. Despite the urgency of the infrastructure build-out, major players including Cenovus have yet to make a final investment decision on those necessary green technologies, leaving a critical piece of the puzzle unsolved even as they expand their physical empire.